


This essay is a collaboration between Farida Khalaf and Alex Randall Kittredge
Gold is holding the $4,950 line, but silver’s physical supply just hit a 50-year vacuum. Here is the data-driven reason the 65:1 ratio is about to snap.
While gold dominates headlines, pushing toward $4,952.32 per ounce in early 2026, silver is quietly building the most severe supply-demand imbalance in modern commodity history.
Since late 2025, silver climbed from $28 to a peak of $121 before today’s violent technical reset to $75.54. Even after this ‘Flash Crash,’ the gold-to-silver ratio which peaked at 125:1 in 2020 has compressed to 65:1. While the historical average is 60:1, the physical reality in the ground is 15:1. The rubber band is snapping.
If you work in tech or follow AI, you already understand what exponential demand curves do to constrained supply. Silver’s fundamentals are on one, and the market hasn’t fully priced it in.
The Three Constraints Converging Simultaneously
Constraint 1: Supply Can’t Respond to Price Signals
Roughly 75% of mined silver is a “hitchhiker” metal, produced as a byproduct of copper, lead, zinc, and gold operations. This means global silver output is a slave to the economics of industrial base metals, not silver’s own price. Even at $75/oz, a silver miner cannot simply “turn on the tap” if the copper mine it’s attached to is scaling back.
For the few primary silver mines left, development timelines typically stretch 7–15 years from discovery to first pour.
Peñasquito (Mexico): 14 years from discovery to commercial production (1996–2010).
Cannington (Australia): 9 years to reach full capacity (1990–1999).
Furthermore, we are mining lower‑grade rock than in the 1990s. Average silver ore grades at many large projects have fallen from around 8–10 grams per tonne to roughly 4–6 grams, forcing miners to move far more rock for the same ounce of metal.
The Bottom Line: High silver prices in 2024–2026 are a “shouted signal” that the supply side literally cannot hear. New production won’t meaningfully hit the tape until the 2030s.
Constraint 2: Industrial Demand is Accelerating on Government Mandates
Silver is the ultimate “Green Metal,” and its demand is now being driven by law, not just markets.
Solar Photovoltaic (PV) Consumption:
2023: ~161 million ounces
2024: ~230 million ounces (Actual)
2026: potentially 260+ million ounces (industry projections tied to ~650+ GW of capacity)
We are seeing a “loading” paradox: while engineers reduce the silver per panel, the industry is switching to N-type cells (TOPCon/HJT) which require higher silver loadings for their increased efficiency. Volume is outrunning efficiency.
The Policy Floor:
EU “Fit for 55”: Legally mandates a 42.5% renewable mix by 2030.
China’s 14th Five-Year Plan: Accelerating toward 1,200 GW of solar/wind, effectively “locking in” silver consumption for the next 48 months.
US Strategic Shift: In November 2025, the USGS officially added silver to the Critical Minerals list, signaling that the era of “cheap, accidental silver” is over.
The AI & EV “Conductivity Premium”:
EVs: A modern EV requires 25–50 grams of silver, roughly 3x more than a gas car. With global sales hitting 17 million units in 2025, the automotive sector is now a 70–75 Moz consumer.
AI Data Centers: This is the “Ghost Demand.” AI-focused servers consume 2–3x more silver than traditional hardware due to the extreme conductivity requirements of high-density chips.
The Verdict: By 2027, total industrial demand is on track to hit 1.3 billion ounces. This is not a “choice”; it is the physical requirement of the energy transition and the AI revolution.
Constraint 3: China Controls Critical Chokepoints
In December 2024, China’s export controls on antimony sent prices up 230% in eight weeks. On January 1, 2026, they applied the same playbook to Silver.
Beijing has replaced its loose quota system with a strict Dual-Licensing Framework. Only state-certified firms producing over 80 tonnes annually qualify. This has effectively orphaned Western manufacturers who relied on Chinese “byproduct” silver, creating an immediate physical vacuum in London and New York.
The Refining Reality:
Mine Production: China accounts for ~14% of mine output.
Refining Capacity: China controls 60–70% of global refined silver supply.
Solar Dominance: China controls 85% of polysilicon and 80% of module assembly.
The West is not just facing a silver shortage; it is facing a “Refining Gap” that takes 5–7 years and billions in CAPEX to bridge.
The Deficit Mathematics
We are entering the sixth consecutive year of structural deficit.
Where is the metal coming from? It’s coming from the “Vaults of Last Resort.” Global ETP (Exchange Traded Product) inventories have been hollowed out. While paper prices crashed to $75.54 today due to margin liquidations, the Shanghai Gold Exchange (SGE) is currently trading silver at a $13 premium over London.
This arbitrage proves the “Signal”: The East is buying the physical metal while the West is selling the paper promise. At current deficit rates, remaining transparent inventories provide only 24–36 months of coverage before hitting “Critical Liquidity Levels.”
The Equilibrium: Between 2027 and 2029, the market will face a binary choice: radical price appreciation or a total halt in “Non-Essential” (electronics/jewelry) production to preserve the solar and defense supply chains.
Historical Precedent: Why This Time Is Different
The skeptics point to the 1990s as proof that “high prices solve shortages.” They remember when photography consumed one-third of global silver (267 Moz) in 1999, only to be wiped out by the digital revolution.
The Comparison is a Category Error:
Demand Destruction vs. Mandated Growth: Photography was a consumer choice. Today’s solar and EV demand is a government mandate. You can’t “digitize” a solar panel’s conductivity.
The Substitution Myth: In January 2026, LONGi announced a shift toward copper-metallized cells, with mass production scheduled for Q2 2026. But copper oxidizes and degrades, lowering panel lifespan. For utility-scale providers, the 1-2% efficiency loss from copper often costs more than the silver it replaces.
The Recycling Gap: Photographic silver was recovered in weeks. Solar silver is “locked” in glass sandwiches with a 25-year warranty.
Annual Recycling Reality: Silver recycling has remained stagnant at 175–185 million ounces for a decade. Higher prices haven’t triggered a wave of “scrap” because the silver in your iPhone or solar panel is simply too expensive to get out for now.
The Gold-Silver Ratio Anomaly
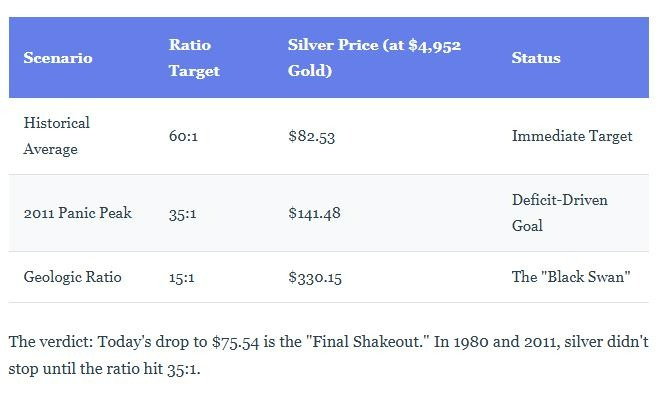
Today’s “Software-mageddon” and the CME’s emergency margin hike to 18% (effective as of yesterday’s close) have created a violent divergence. While Gold hit an all-time high of $4,952.32, Silver was liquidated down to $75.54.
Early February 2026 Real-Time Positioning:
Gold: $4,952.32/oz (Record High)
Silver: $75.54/oz (Flash Crash Low)
Live Ratio: 65.5:1
The Historical Context:
Long-term average (post-1970): ~65:1
The “Value Zone”: 80:1 and above (Historically a 100% “Buy” signal for silver)
The “Exit Zone”: 30:1 to 40:1 (The peak of the 1980 and 2011 runs)
Ratio Reversion Scenarios (At $4,952 Gold):
Why the “Old” 88:1 Ratio is Dead
Many analysts are still using the 88:1 figure from early 2025. That was a “Surplus World” number. In the 2026 Deficit World, the floor has shifted.
The Gold Floor: Central banks (especially the BRICS+ bloc) have floor-priced gold at $4,500+.
The Silver Spring: Because silver is a much smaller market, it is reacting to gold’s moves with a 2.5x beta.
Three Probability-Weighted Scenarios
Scenario 1: Gradual Squeeze (55% probability): Despite today’s margin-call liquidation, the deficit remains. Physical stocks in London and New York drain at record velocity while industrial buyers use this price dip to lock in physical agreements.
Catalyst: A “Short Squeeze” triggered by COMEX delivery defaults in Q2 2026.
Price Path: Recovery to $95–$110 by Q4 2026.
Scenario 2: China Intervention (30% probability): Beijing doubles down on its January 1 licensing system, citing “Strategic Reserve Priority.” They move from restricting who can export to restricting how much.
Catalyst: China effectively closes the “Silver Valve” to Western competitors.
Price Path: Asymmetric Upside. Silver enters “unobtainium” territory, potentially spiking to $150–$180.
Scenario 3: Demand Destruction (15% probability): The “Software-mageddon” tech selloff turns into a full-blown global credit crunch. High interest rates from a hawkish Fed (the Warsh effect) crush manufacturing.
Catalyst: Solar installation growth turns negative for the first time in a decade.
Price Path: A brutal re-test of the $35–$45 support levels.
What Could Break This Thesis
No thesis is bulletproof. To remain objective, we have to monitor the “Escape Hatches” that could resolve the deficit without a massive price spike:
No thesis is bulletproof. We have to monitor the “Escape Hatches”:
Hyper-Thrifting & Substitution: If the top 5 solar manufacturers successfully switch to silver-free (copper) designs by Q4 2026, roughly 150–200 Moz of annual demand vanishes.
The “Warsh” Credit Crunch: If newly nominated Fed Chair Kevin Warsh pivots to an aggressive “Hard Money” stance, the dollar surge could crush industrial demand.
The “Shadow Inventory” Release: If unreported silver hoards from sovereign wealth funds flush out at $120, the vacuum could be filled faster than reported.
The Bet: None of these factors can scale fast enough to bridge a cumulative 820 million ounce deficit before 2028.
What The Data Requires You To Believe
For silver to remain at current levels ($75–$80) or decline back to the $30s, your “Bear Case” requires you to believe five improbable things simultaneously:
Instant Mine Supply: That the 7-15 year development cycle can be compressed into 18 months.
Solar Capitulation: That the $369B in US IRA incentives and China’s 14th Five-Year Plan will be abandoned.
Frictionless Substitution: That manufacturers will risk 25-year warranties on unproven copper cells.
Invisible Vaults: That the 27% decline in COMEX/LBMA inventories is “fake news.”
Monetary Stability: That gold will stay at $4,950 while silver decouples and crashes, defying history.
The Verdict: The data shows that the “Equilibrium” price for silver hasn’t been found yet. Today’s volatility is a liquidity event, not a fundamental shift.
Monitoring Framework
Bookmark this checklist for tracking how the thesis evolves:
Supply-Demand Indicators:
Silver Institute quarterly reports: Watch for revisions to the 180–215 Moz deficit forecast.
COMEX Registered Stocks: If the inventory drops below the 100 Moz psychological floor, the delivery default risk becomes systemic.
Shanghai-London Spread: Widening premiums in Shanghai (currently $13+) indicate that the East is hoarding physical metal while the West liquidates paper.
The “Copper Substitute” Watch:
LONGi Green Energy (Q2 2026): Monitor the rollout of their base-metal BC cells. Success here is the only “Silver Bullet” the bears have.
Thrifting Rates: Follow the SMM (Shanghai Metals Market) analysis. If thrifting exceeds 17% in 2026, the deficit may narrow faster than expected.
Geopolitical Trigger Points:
China Export Licensing: Watch for the “44 Approved Firms” list. Any contraction in this number is a de-facto export ban.
Strategic Stockpiling: Monitor State Reserve Bureau (SRB) announcements. A Chinese “Silver Buyback” would instantly send the ratio toward 30:1.
The Data Is Clear
Five consecutive years of 150-200+ million ounce structural deficits. A mine supply that is physically incapable of responding until the 2030s. A technological revolution in solar and AI that treats silver as a non-negotiable requirement.
Today, on February 6-7, 2026, the gold-silver ratio has stretched back to 65:1 due to a technical margin flush. History suggests this is not a collapse, but a “coiling.” The question isn’t whether the data matters, the question is whether you are willing to ignore the math of the most severe supply-demand imbalance in modern history.
Data sources:
Silver Institute: silverinstitute.org
CME Group: cmegroup.com
World Gold Council: gold.org
Disclaimer: This is not investment advice. The numbers presented here are based on early February 2026 market volatility. Please double-check all calculations before making any decisions.
If you enjoyed this guest post, visit ARK Strategy by Alex Randall Kittredge, where he helps professionals building careers in systems not designed for them.

Incredible breakdown, Farida and Alex!
I agree 100% with your demand-side analysis. I’m seeing this exact crunch in my own research on AI infrastructure and semiconductors. The power density of the new AI data centers is insane... they literally need silver’s conductivity because copper hits its thermal limits at those loads. Raw physics DEMANDS silver.
I used to look at my old box of silver half-dollars as just a fun keepsake. But looking at the price action, even with the recent pullback, I’m glad I held onto them. This feels less like a market fluctuation and more like a regime change. 👀
Cordially,
Mike D
Just read your piece on the $75 silver flash crash and I love how clean you make it!!! You don’t romanticize the candle. You name the mechanism!!
A move like that is rarely “the truth.” It’s the market running a quick stress test on human nerves, headlines, and weak hands. The trap is not the dip. The trap is the story people tell themselves during the dip..